
Spanish Property Prices Are Rising. But the Bank May Value Your Home for Less
30 September, 2026 | Antonio Beltrán
Imagine finding the property you have been looking for in Spain.
It has a terrace. It is close to the sea. You can already picture yourself having breakfast there, welcoming your family and spending part of the year away from the cold weather back home.
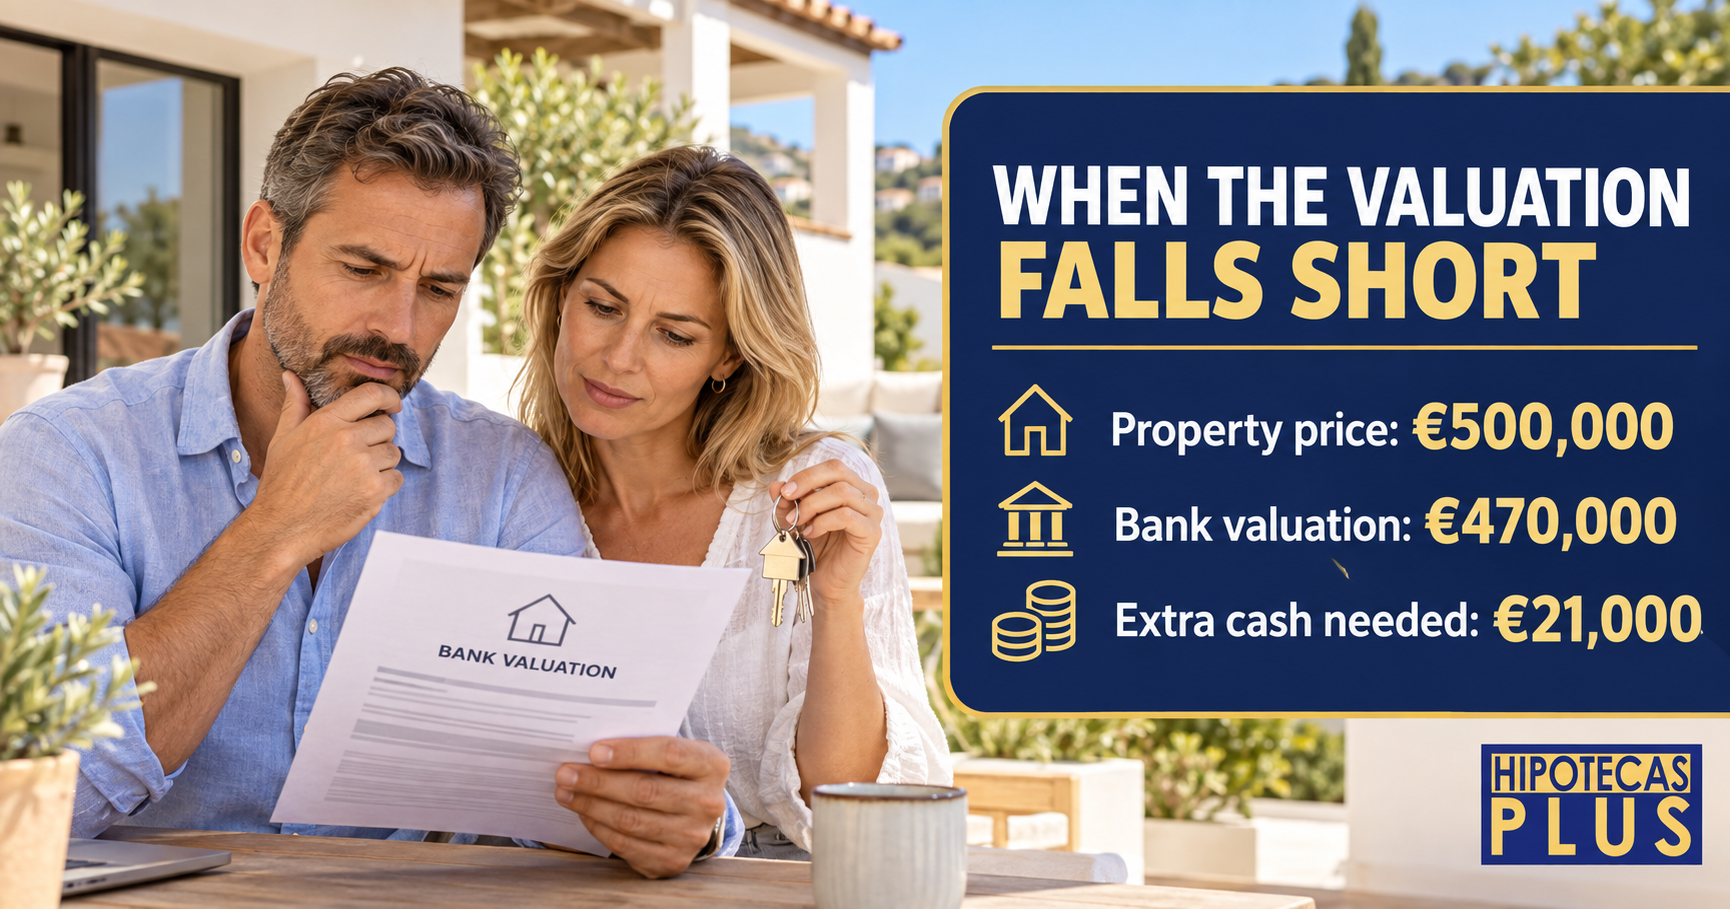
The asking price is €500,000.
The estate agent tells you that other buyers are interested, so you decide to make an offer. You may even be ready to sign a reservation agreement or pay a deposit to avoid losing the property.
Then the mortgage valuation arrives.
The property is not valued at €500,000. It is valued at €470,000.
Suddenly, you need an additional €21,000 that you had not included in your calculations.
Not because the bank has changed its mind.
Not because your income is insufficient.
But because your mortgage is not always calculated using the price agreed with the seller.
Seventy per cent does not always mean 70% of the purchase price
For many non-resident mortgage applications, a Spanish bank may finance up to 70% of the lower of:
- The purchase price.
- The bank valuation.
Using our example:
- Purchase price: €500,000.
- Mortgage valuation: €470,000.
- Maximum financing: 70% of €470,000.
- Resulting mortgage: €329,000.
If you calculated 70% of the purchase price, you expected a mortgage of €350,000.
The difference is €21,000.
You must provide this additional amount from your own funds, on top of the deposit, purchase taxes, transaction costs and professional fees.
If your income is paid in a currency or comes from a country that the bank considers higher risk, financing may be limited to approximately 50%. In that situation, the effect of a low valuation can be even more significant.
Valuation figures are rising, but not equally across Spain
According to the latest figures published by the Spanish Mortgage Association using data from Spain’s Ministry of Housing, the average valuation of unrestricted residential property increased by 12.5% year-on-year in the second quarter of 2026.
However, the quarterly increase slowed to 1.7%.
There were also substantial regional differences:
- Valencian Community: +15.7% annually.
- Alicante: +14.1%.
- Andalusia: +13.8%.
- Málaga: +13.8%.
- Balearic Islands: +13.1%.
- Canary Islands: +14.2%.
- Catalonia: +10.1%.
- Province of Barcelona: +9.7%, but down 0.1% compared with the previous quarter.
The complete figures are available in the Spanish Mortgage Association’s report.
These percentages do not mean that every individual property has increased in value by the same amount.
A mortgage valuation considers the precise location, size, condition, comparable sales, land registry and planning situation, and the specific characteristics of the property.
Rising market prices do not guarantee that the bank will accept the seller’s asking price.
The real danger is discovering the shortfall after signing
A low valuation is not necessarily the biggest problem.
The real risk arises when you have already entered into a binding agreement.
If you sign a deposit contract before your financing has been properly assessed and the mortgage is lower than expected, you may have to:
- Contribute considerably more cash.
- Find another lender under severe time pressure.
- Renegotiate the purchase with the seller.
- Withdraw from the transaction.
- Lose your deposit if the contract does not protect you.
That is why asking, “Can I obtain a 70% mortgage?” is not enough.
The correct question is:
How much will the bank lend against this specific property, and how much cash will I need under a reasonably cautious scenario?
Confirm the financing before committing to the purchase
At HipotecasPlus, we review your income, existing debts, currency, country of residence and available savings before you commit to buying a property.
We calculate the financing you may realistically obtain and the total amount you will need to contribute. Once you have identified a property, we can also coordinate the valuation and review the transaction before you sign a deposit agreement that could put your money at risk.
Buying a property in Spain should be an exciting experience.
The dream matters.
But real peace of mind comes from knowing, before you sign, that the numbers work and the transaction is under control.
Have you found a property in Spain? Do not sign a reservation or deposit agreement until you have checked both the financing and the potential valuation outcome.